
● What you get
Your NHS pension, worked out in full
A personal PDF report, emailed to you within 7 working days of finishing your questions. Part one works from your pension record as it stands. Part two works through two futures you design.
IN YOUR REPORT
Every figure on this page is an illustrative example, at today’s prices.
PART ONE · AS YOU ARE
Your pension as it stands
Worked out from your annual pension statement, assuming nothing changes from today. It answers questions like these:
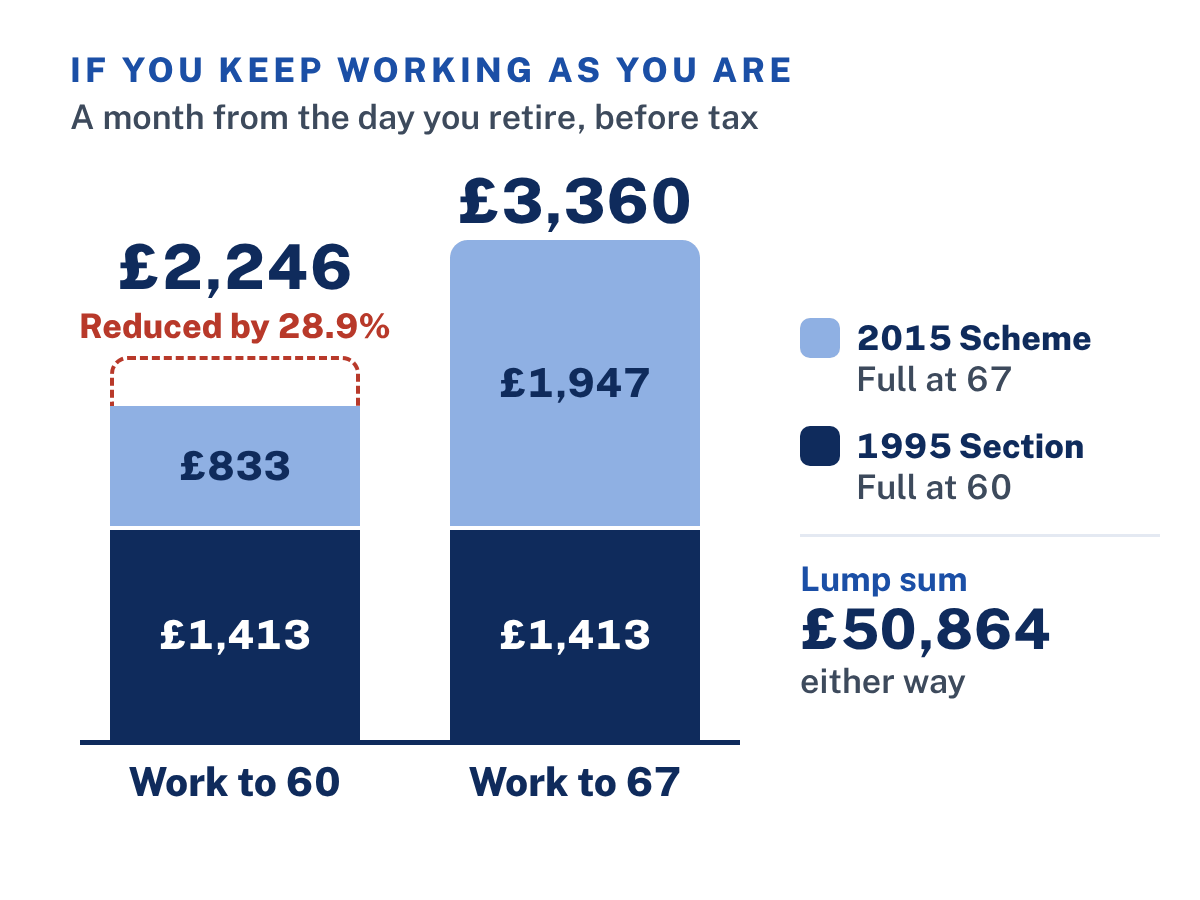
What would I get if I keep working to my normal pension ages (60 and 67 for many people)?
If I go early, which parts of my pension are reduced, and by how much?
When does my State Pension join in?
If I wait for the later age, how long does it take to catch up?
What would a bigger lump sum cost me each month, and how does the tax-free limit apply?
What does the McCloud choice pay me each way?
Do I have to stop work and take my pension on the same day?
PART TWO · AS YOU CHOOSE
Two futures you design
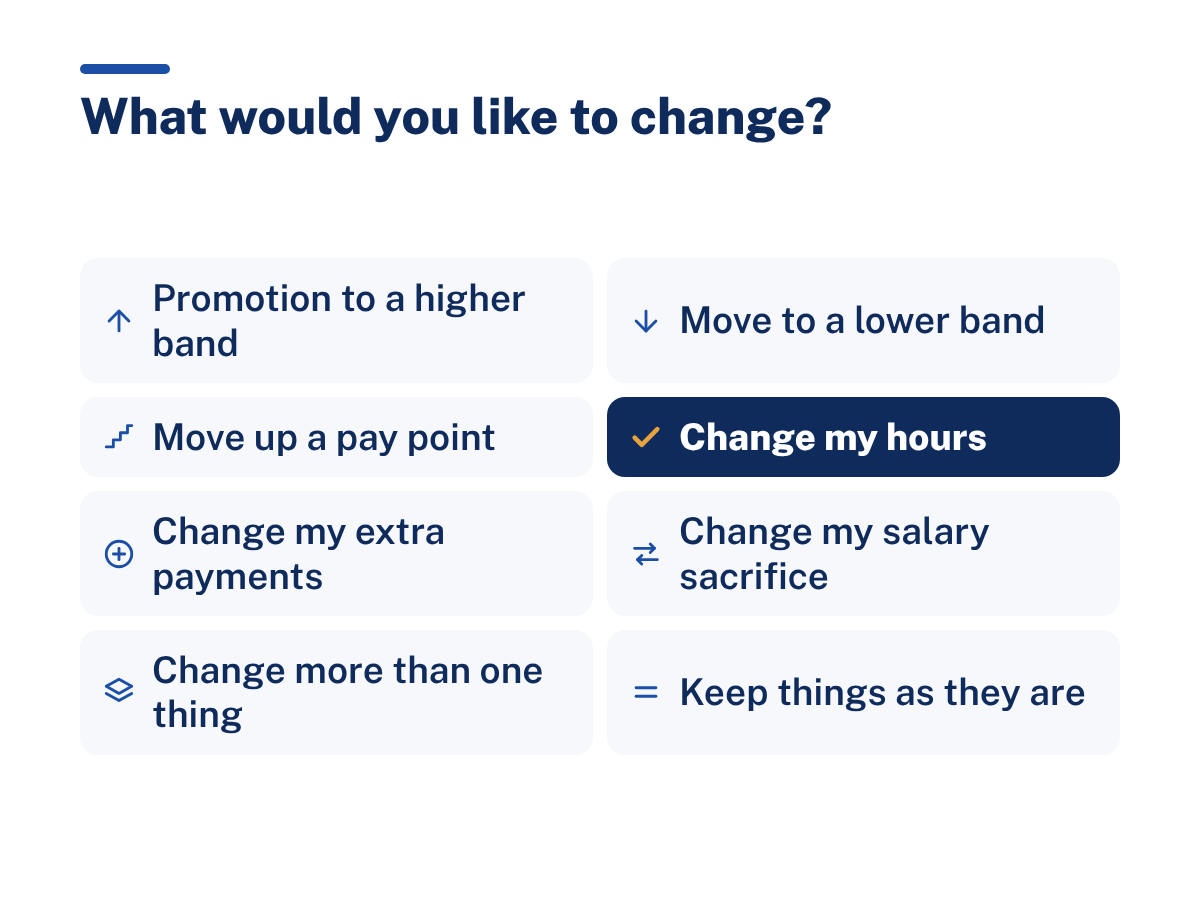
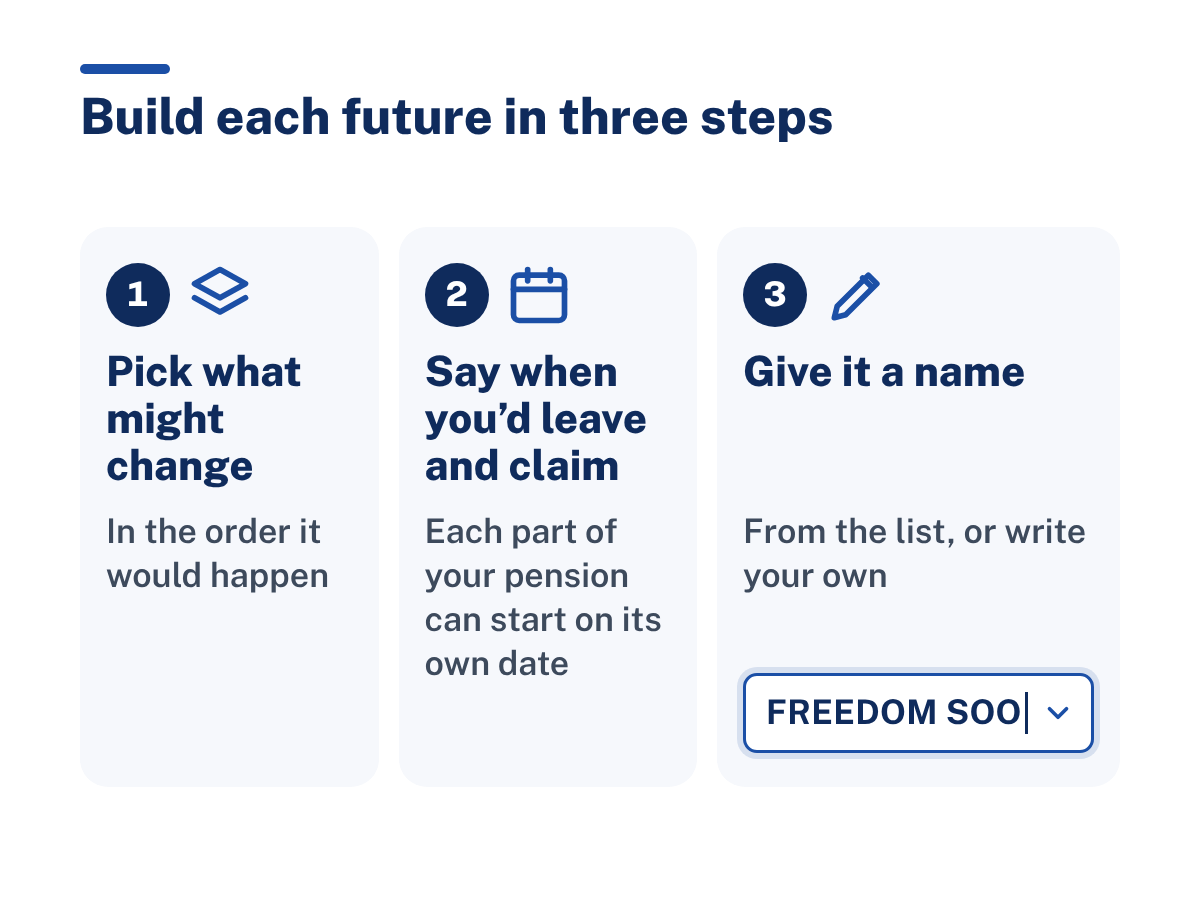
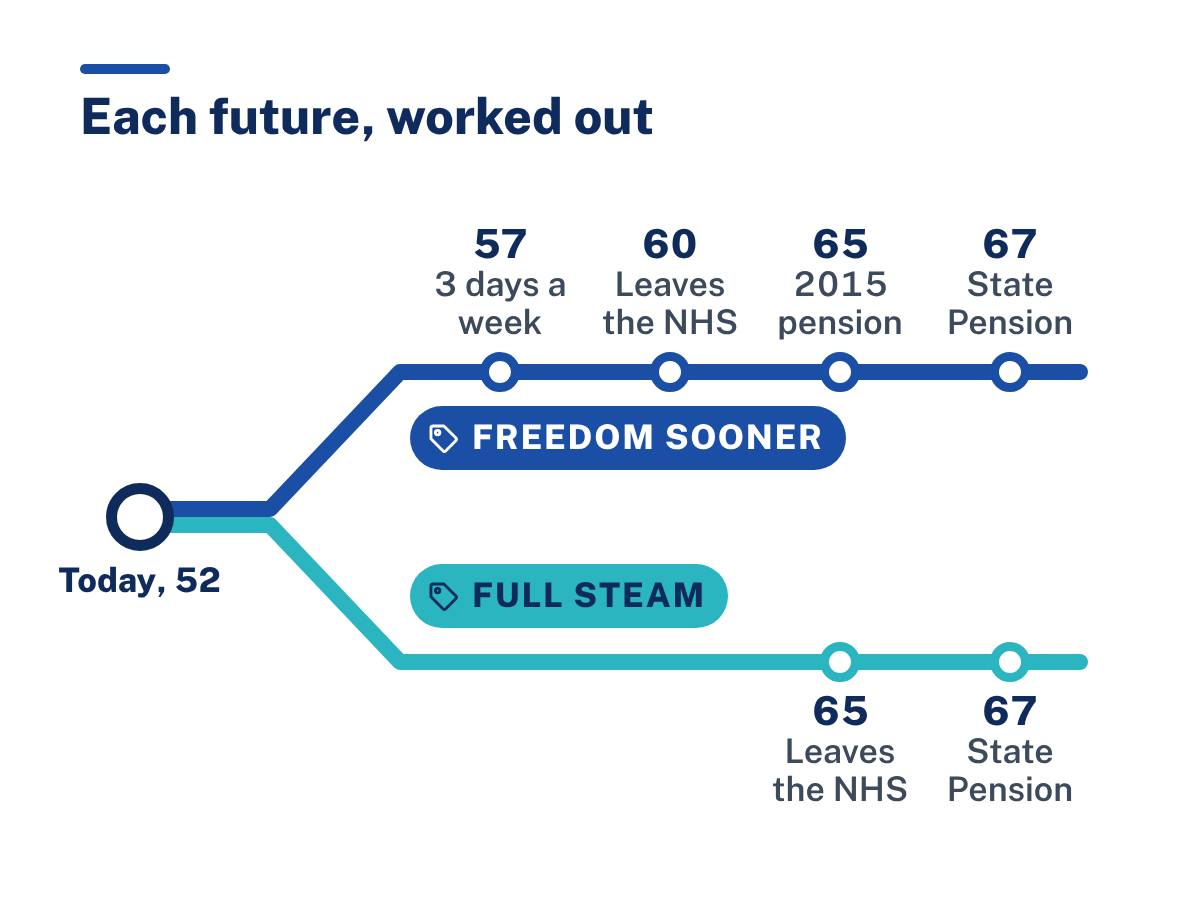
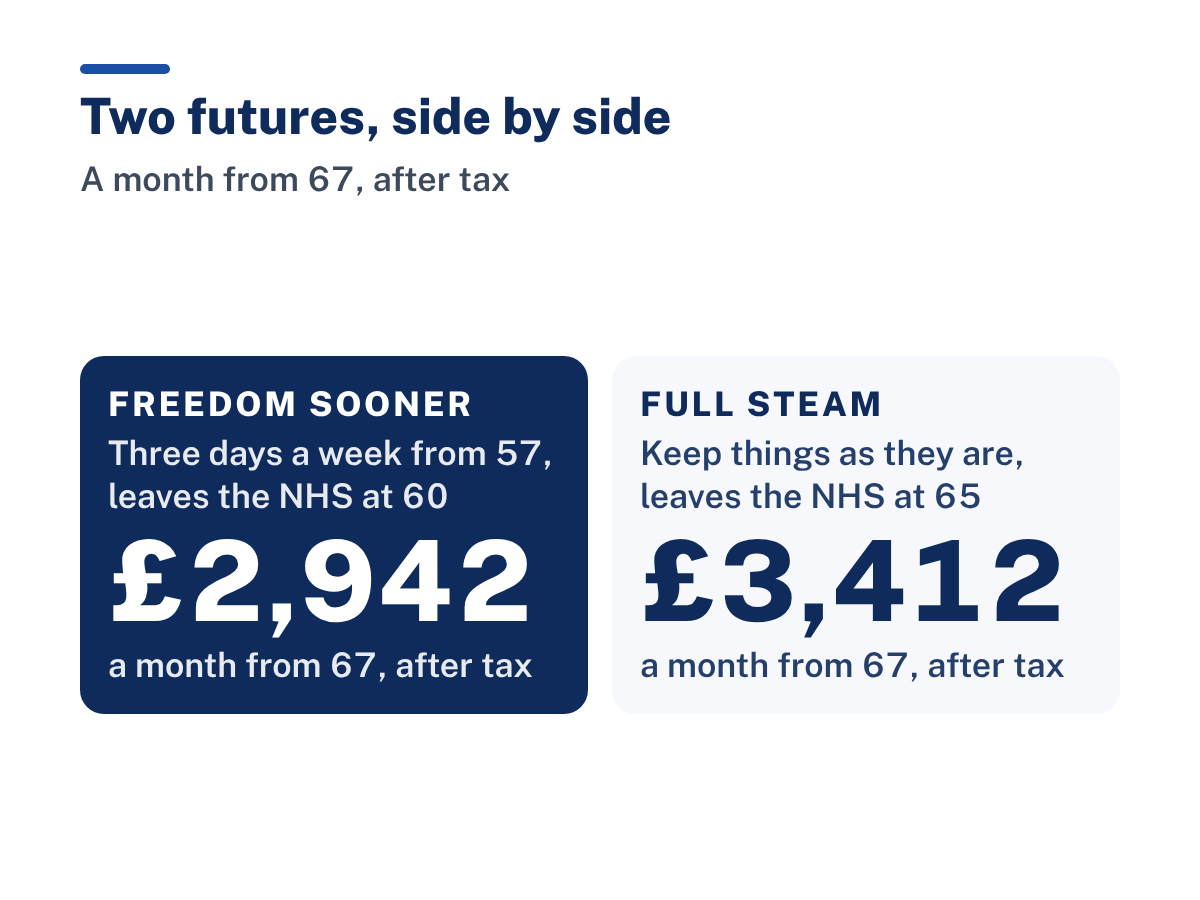
Pick what might change, in the order it would happen: a promotion, a move up a pay point, a lower band, different hours, a career break, more or less salary sacrifice, and when you leave the NHS and claim your pension. Then name each future. Freedom Sooner and Full Steam are two names from the list, or use your own.
Each future is worked out before and after tax and placed on The Lifestyle Gauge. Then both go through The Lump Sum Ladder and The Seven-Year Choice, so you can compare them.
IN YOUR BANK
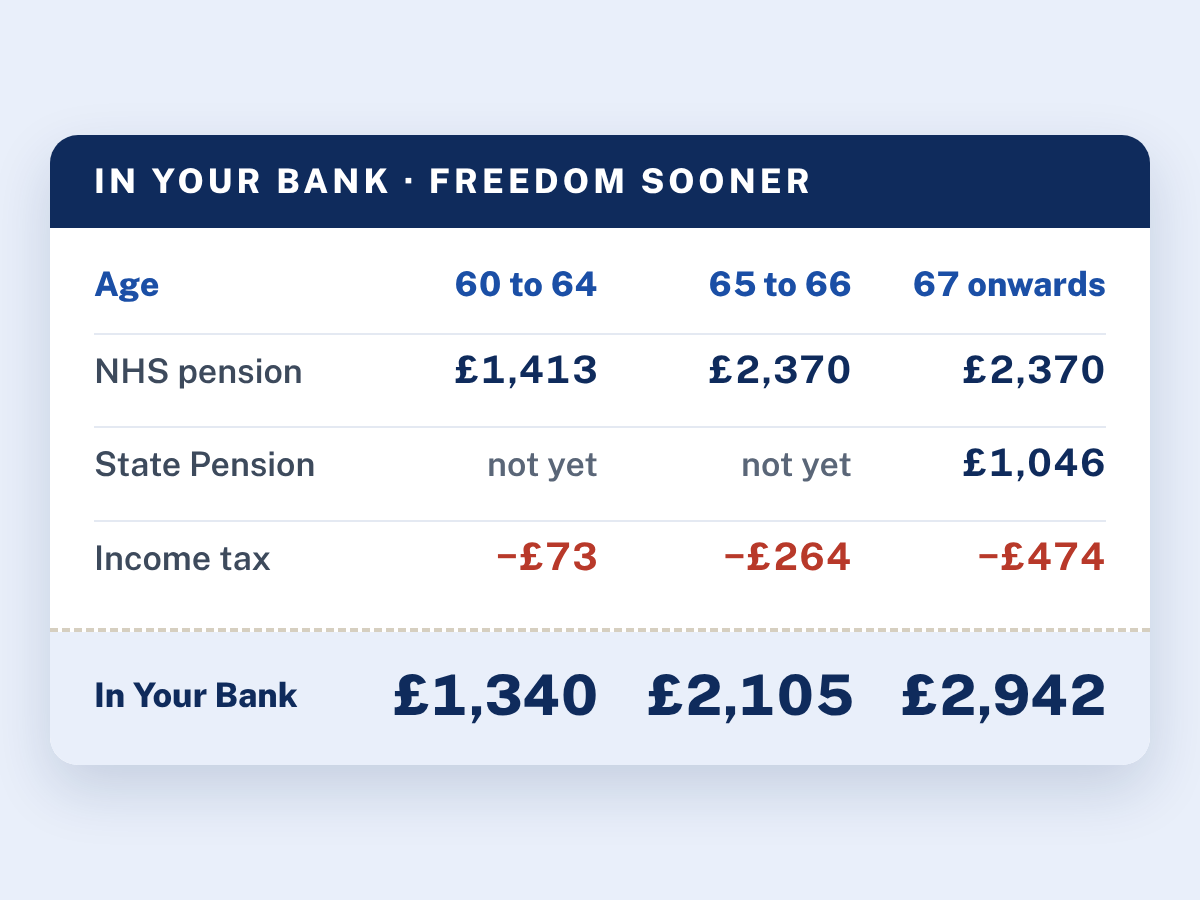
What lands in your account each month
Your NHS pension and State Pension added together each month, after income tax, for each future. If parts of your pension start at different ages, you see each step as it arrives. The tax is an illustration using today’s rates and the standard personal allowance, not tax advice.
THE LIFESTYLE GAUGE
What your pension pays for
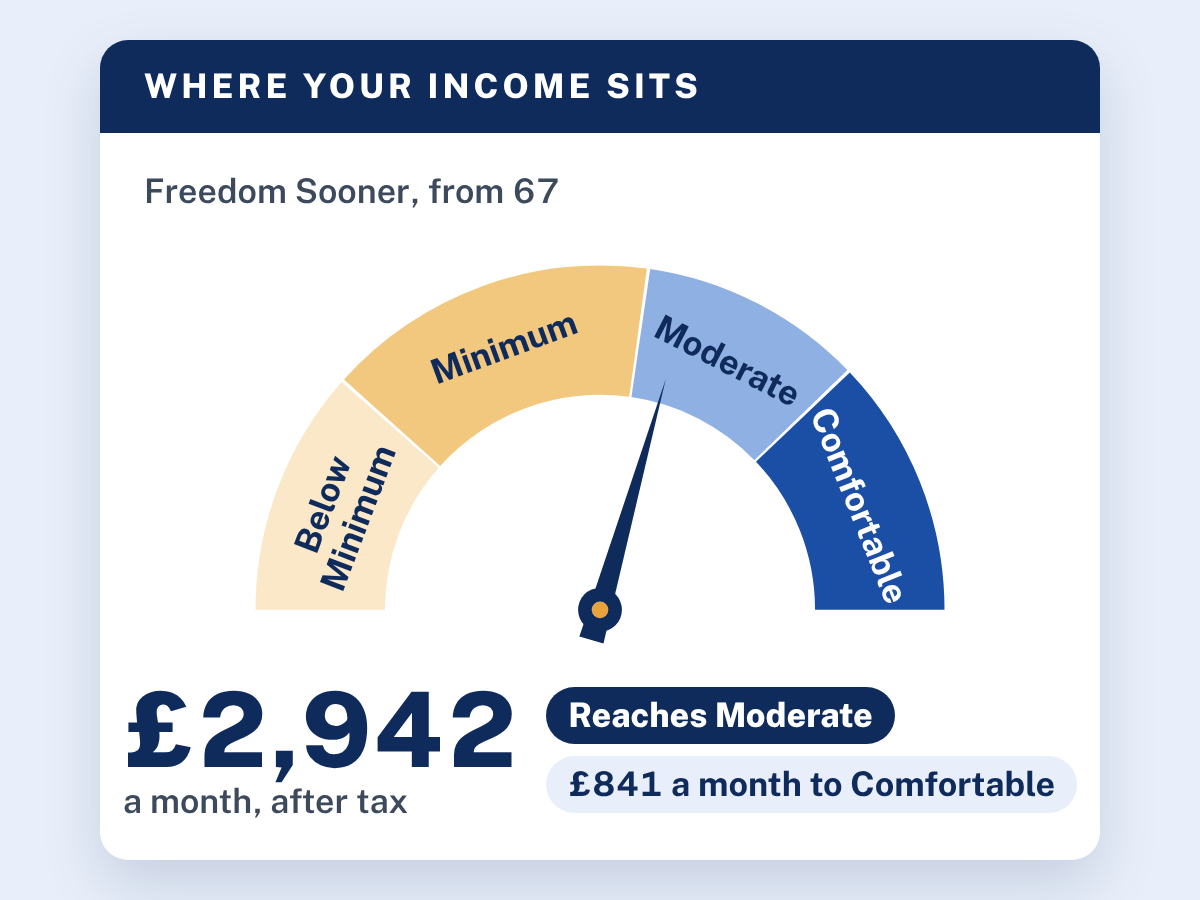
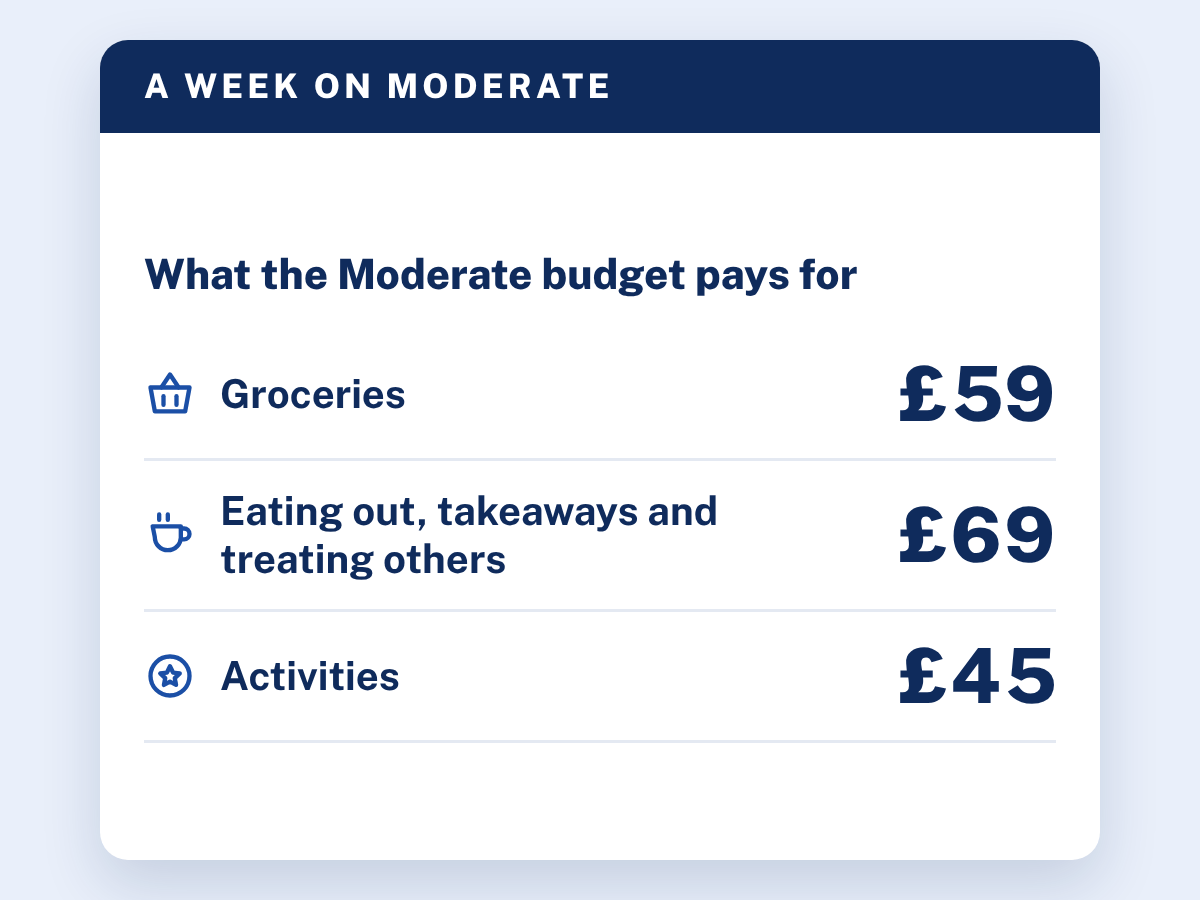
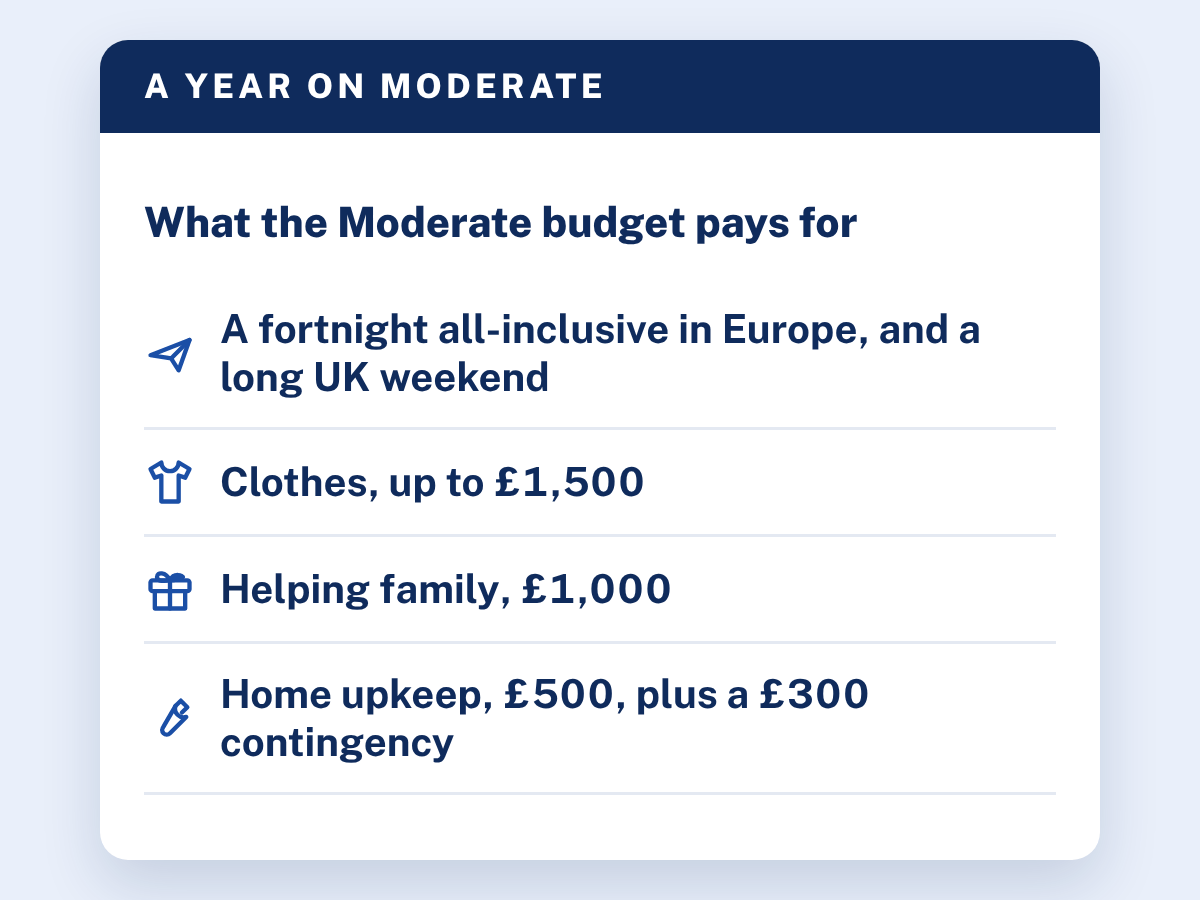
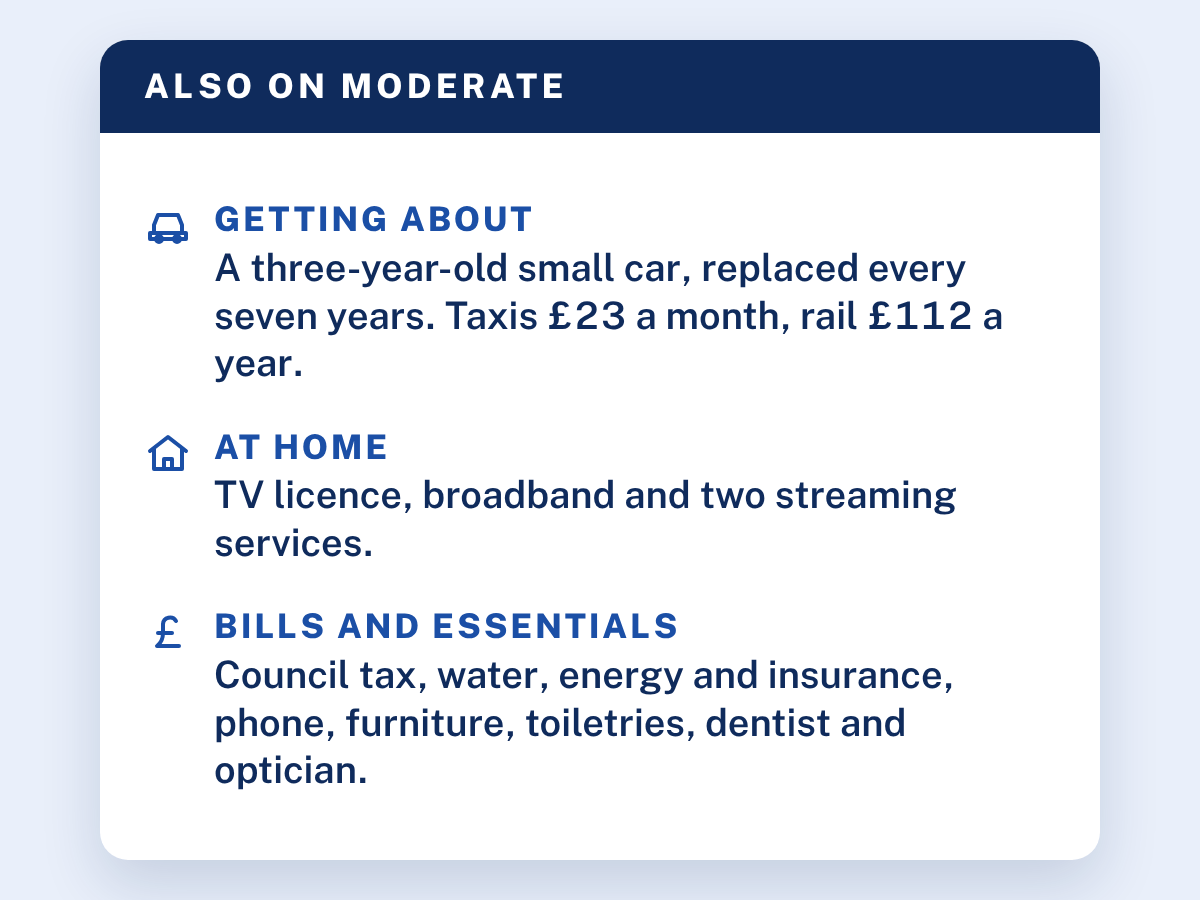
See what your income buys. The gauge sets each future against the Retirement Living Standards, three standards for what retirement costs, and shows which one you reach, what you’d have left over after that budget, and how far you are from the next.
One person, a month after income tax. Source: Pensions UK/Loughborough University Retirement Living Standards, the property of and provided by both. For illustration and guidance only; not financial advice.
THE LUMP SUM LADDER
Your lump sum options, rung by rung
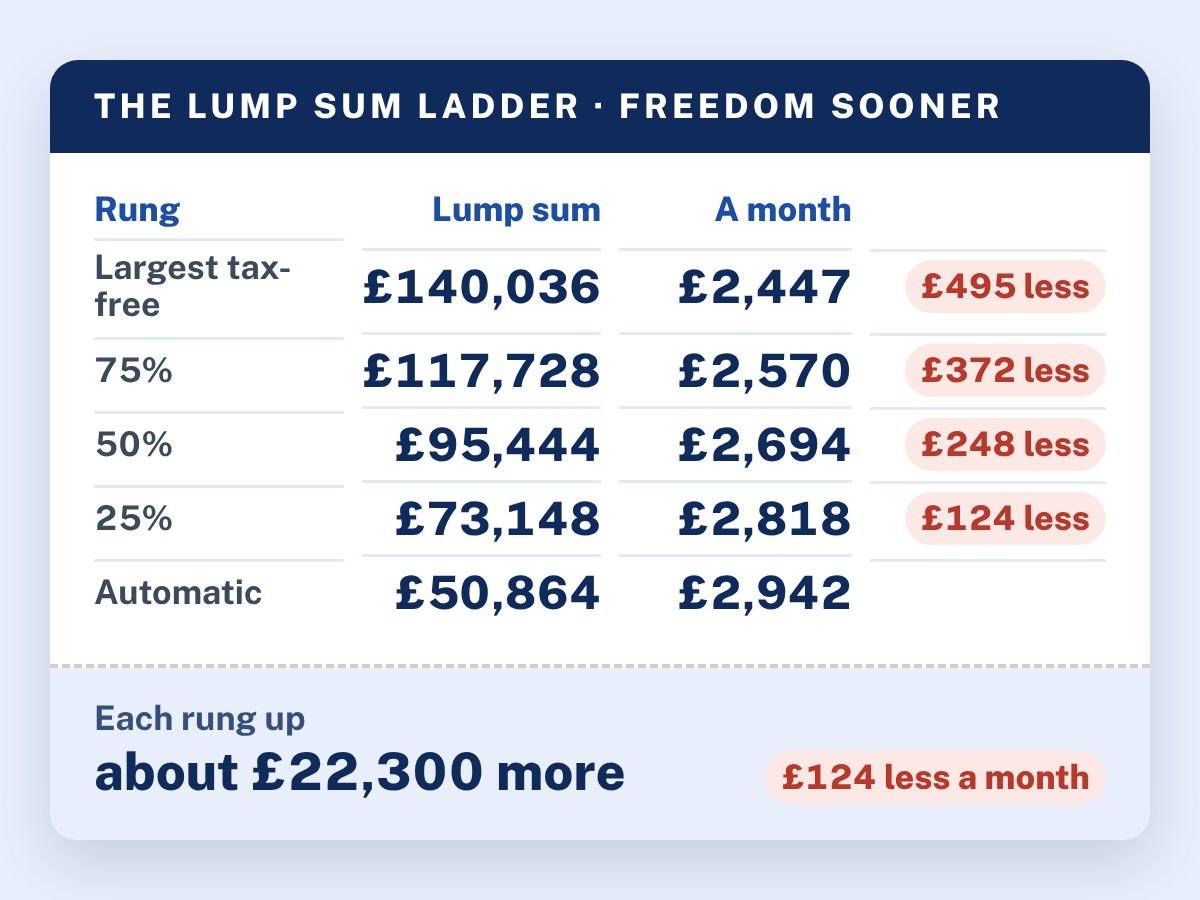
Pay off the mortgage, help your children with a deposit, or keep more coming in each month. The Lump Sum Ladder shows the steps from the smallest lump sum to the most you can take, in each future, and what each one would leave you to live on, after tax.
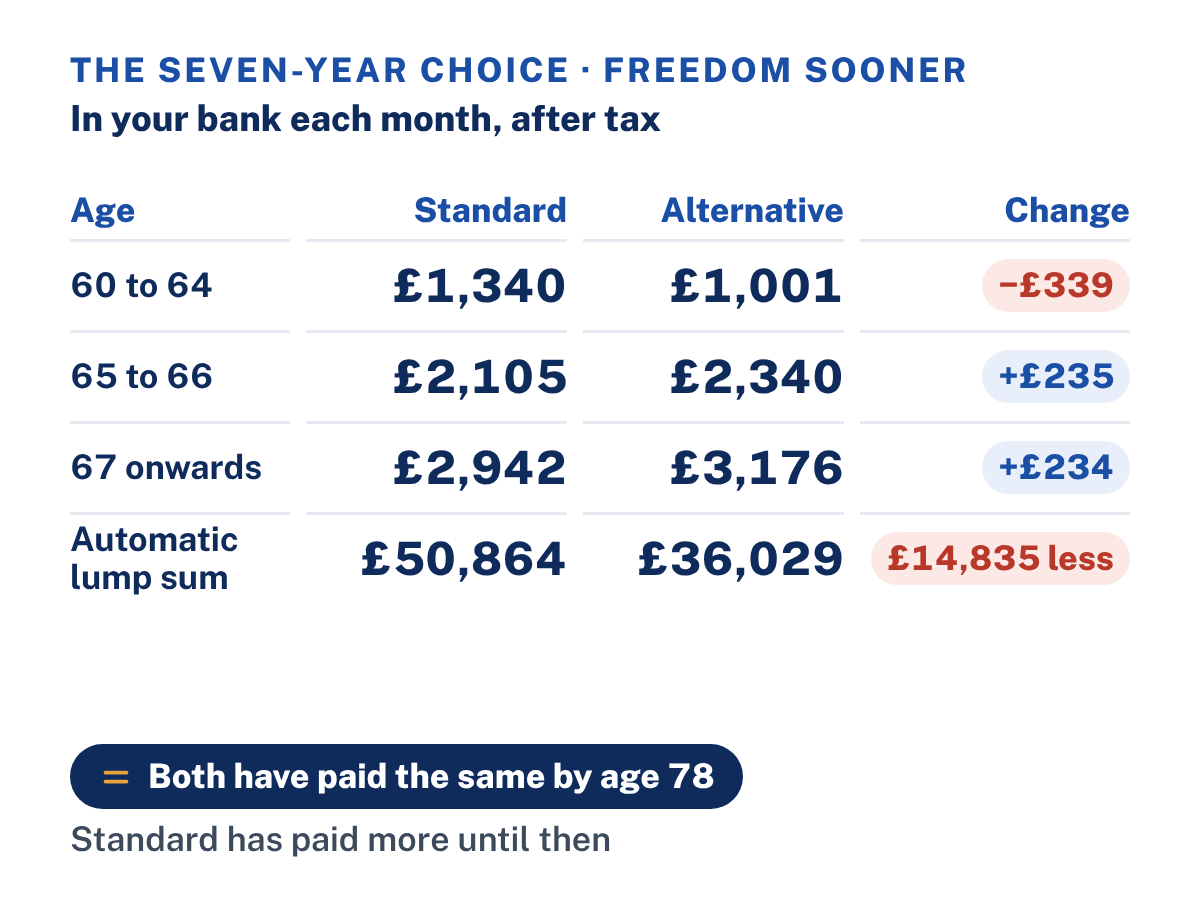
THE SEVEN-YEAR CHOICE
The McCloud choice in plain English
If you were in the scheme on or before 31 March 2012, paid in at some point between April 2015 and March 2022, and had no break of five years or more, you’ll choose how those seven years count when you claim your pension.
The report shows both options at both retirement ages: the monthly pension, the lump sum and your partner’s pension. Then it sets the choice against your own two futures, after tax. It shows the numbers and leaves the choice to you.
If you joined on or after 1 April 2012, the choice doesn’t apply.
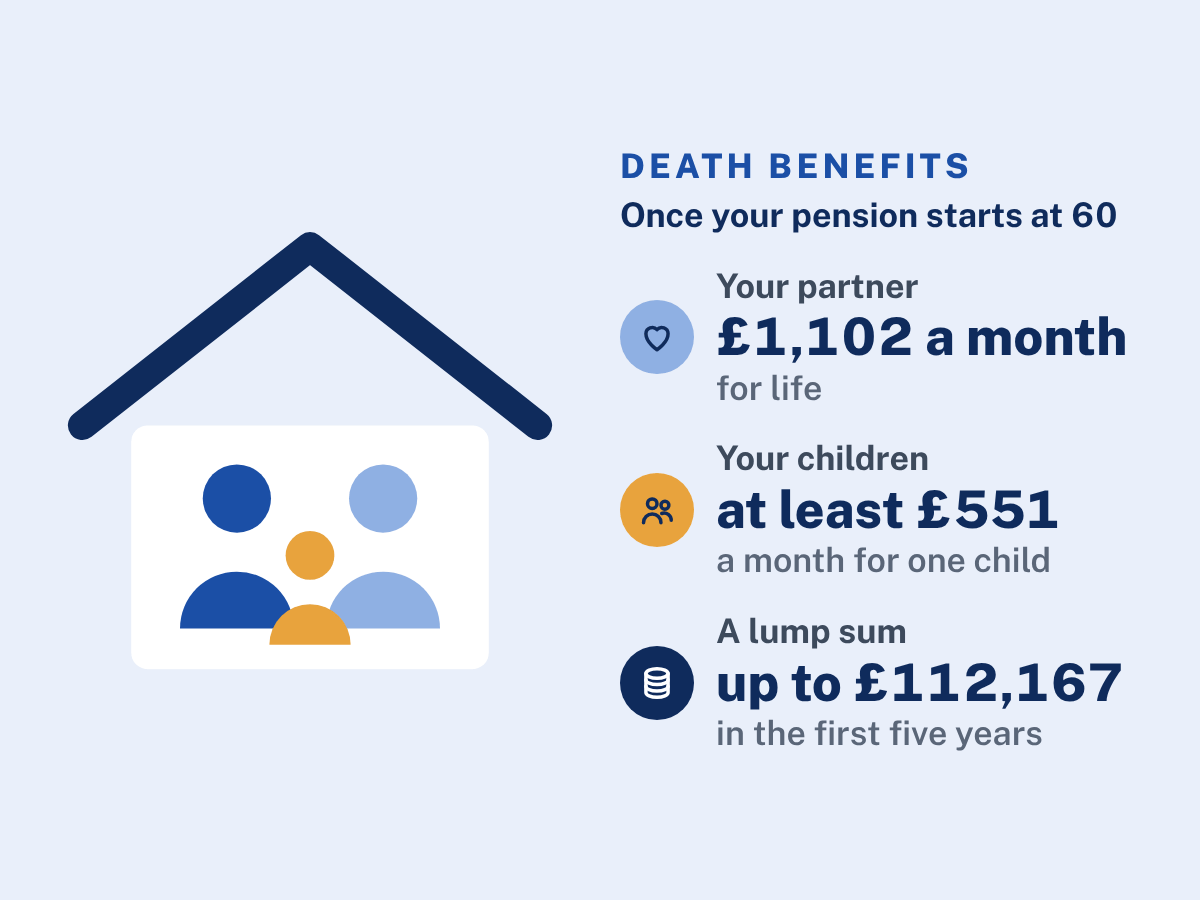
DEATH BENEFITS
Peace of mind for your family
One less thing to wonder about. Your report shows what your NHS pension would pay your partner and children if you died, at every stage, and whether there’s anything to do now so it goes to the right people.
Your partner and children, whether you’re still working or retired
What changes it, including the lump sum you take and the Seven-Year Choice
Who counts as your partner or child for these benefits, and whether you need to fill in any forms now
Also in your report
Four more things your report covers.
When waiting pays off
A pension that starts later pays more each month. Your report shows how many years it takes for that higher pension to make up for the years you didn’t draw it.
Stopping work and starting your pension
Your last day at work and your first pension payment can fall on different dates. The scheme allows three ways to arrange this, and each comes with rules on your pay, your hours and when you can come back. Your report explains all three.
Who gets what if you die
Your pension pays out to your family if you die, but the scheme decides who counts. Some of that depends on forms you may have filled in years ago, or never filled in at all. Your report shows who would receive what, and what you might need to update.
What to do next
The steps and deadlines the scheme sets: what to check now, what to do before you decide, and how to claim. Each form is named, so you know what to ask for. It also lists where to get free help, and how to find a regulated adviser if you want advice.
BEFORE YOU BUY
Check it covers you
Not the right report if
You’re a doctor or dentist at any grade, including consultants, or a Very Senior Manager (editions coming soon)
You’re a GP or a dentist in general practice
You’re paid outside Agenda for Change bands
You’re in the NHS pension scheme for Scotland or Northern Ireland
You already receive some or all of your NHS pension
You have Mental Health Officer status
You chose to move your 1995 Section service into the 2008 Section in the Choice exercise (having service in both sections is fine)
You don’t have a 2025 or 2026 annual pension statement (for example, if you joined recently)
You know NHS Pensions can’t give you an accurate annual pension statement at the moment
Not calculated in the report
Ill health retirement
Partial retirement, and retire and return: the report explains how both work
A reduction for pension sharing on divorce
A reduction for Scheme Pays
Pension tax above the annual allowance
A future move outside Bands 1 to 9
60 founding places at £350 £250
Founding bonus: 15 minutes online with me after your report arrives.
Founding price. £350 from the next round. Opens Wednesday 25 November at midday.
Information, not financial or tax advice
Your report shows what the scheme would pay in the futures you choose. It won’t tell you what to do. Frontline Futures is not a regulated financial adviser or an accountancy practice.